


Audit Committee
Audit Committee
The Audit Commitee was established by the Board of Commissioners to achieve the most efficient and effective audit results, the Company developed and endorsed working guidelines known as the Audit Committee Charter.
Composition and Profile of the Audit Committee
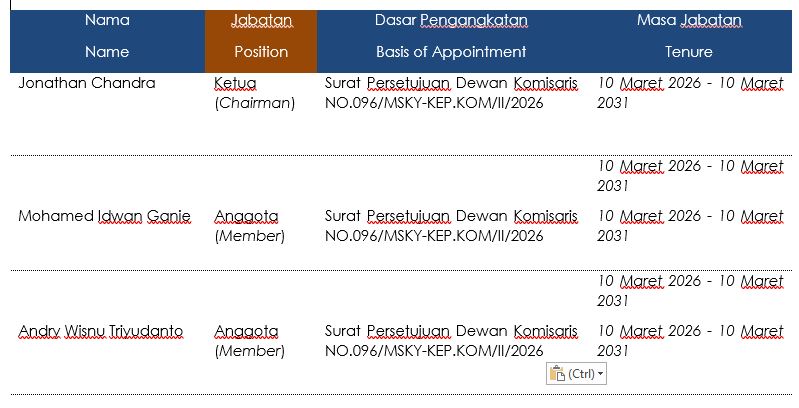
The Company’s Audit Committee consists of 3 (three) members, comprising 1 (one) chairman and 2 (two) members, as follows:
The Independency of Audit Committee
Financial Services Authority Regulation No. 55/POJK.04/2015 on Establishment and Guidelines of the Audit Committee stated that the Audit Committee consists of at least 3 (three) members that comes from Independent Commissioner (appointed as Chairman of the Audit Committee) and Parties outside of the Public Company, which appointed and dismissed by the Board of Commissioners. All members of the Audit Committee have no affiliation with either Board of Commissioners and Directors or Shareholders of the Company. In performing its function, the Audit Committee has no personal conflic of interest and is not under pressure from any party. The members of Audit Committee of the Company are independent parties who carry out their duties and responsibilities professionally and independently.
Work Guidelines of Audit Committee
The Company has compiled the Audit Committee Charter as a guideline for the Audit Committee in carrying out its duties and responsibilities efficiently and effectively. The Charter was last updated and ratified by the Board of Commissioners based on the Decree of the Board of Commissioners No.020/MSKY-Kep.Kom/III/17 dated March 16, 2017. TheCompany has extended the tenure of Committee Audit members until March 15, 2022. The Work Guidelines cover the structure of membership, membership requirements including requirements on competency and independency, duties, responsibilities and authorities, as well as meetings, reporting and budget.
Work Guidelines of Audit Committee
In assisting the monitoring function of the Board of Commissioners, Audit Committee hold several duties and responsibilities as follows:
- Reviewing the financial information issued by the Company to public and/or authorities, such as financial statement, projection and other reports in accordance to Company’s financial information;
- Reviewing the Company’s adherence to the law and regulations related to the Company’s activities;
- Providing independent opinion in case of dissents between management and Public Accountant on their services;
- Providing recommendation to the Board of Commissioners in appointing Public Accountant based on its independencies, scope of work, and fee;
- Reviewing the implementation assessment by Internal Auditor and monitoring follow-up implementation by Board of Directors on Internal Auditor’s findings.
- Reviewing the implementation of risk management activity conducted by the Board of Directors, if the Company does not have risk-monitoring function under the Board of Commissioner;
- Reviewing complaints related to accounting process and report on Company’s finance;
- Reviewing and making recomendation to the Board of Commissioners in accordance to potential of Company’s conflict of interest;
- Ensuring the confidentiality on the Company’s document, data and information.
Authorities of Audit Committee
The Audit Committee has the following authorities:
- Accessing the Company’s document, data, and information about its employee, funds, assets, and the Company’s resources as needed;
- Communicating directly to the employees including the Board of Directors and parties who conducting internal audit function, risk management, and Public Accountant in accordance to Audit Committee’s duties and responsibilities;
- Involving independent party outside the required Audit Committee to support duties implementation (if needed);
- Conducting other authorities as needed by the Board of Commissioners.